
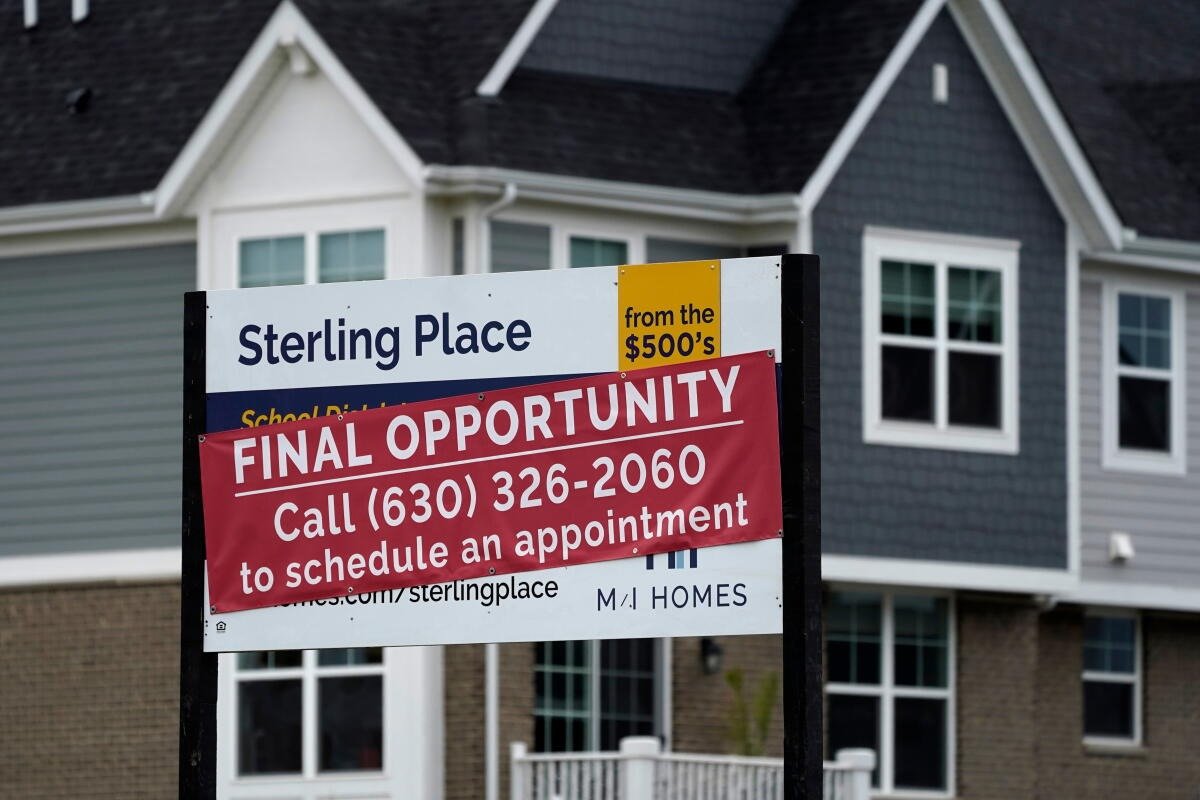
Housing market experts are assessing significant implications as Mortgage rates climb Feds hike consequences take hold, with borrowing costs reaching their highest level in more than a year following the central bank’s first interest rate increase since 2023.
Industry analysts note that mortgage rates had already been climbing steadily since earlier this year in anticipation of exactly this kind of Federal Reserve action, meaning today’s actual increase confirms a trend rather than introducing entirely new upward pressure on home borrowing costs.
A senior director at a major credit rating agency indicated that this rate environment will likely slow home purchases and mortgage refinancing activity through the remainder of the year, creating additional pressure on mortgage company profitability across the broader housing finance industry.
Real estate economists suggest that mortgage rates are likely to remain elevated for the foreseeable future, given indications that the Federal Reserve intends to continue raising rates, a scenario that will keep some prospective buyers hesitant to enter the market despite otherwise stable economic fundamentals.
This higher rate environment represents a marked contrast to conditions seen just one year earlier, when rates had dropped below six and a half percent, suggesting significantly reduced year over year momentum for home sales activity during the final quarter of this year.
Despite these headwinds, some housing market analysts point to underlying economic strength as providing a floor for housing demand, even as elevated rates create genuine affordability challenges, particularly for first time homebuyers entering the market with limited existing equity.
Industry representatives from major mortgage lenders note that while elevated rates squeeze affordability, current housing inventory levels have reached a six year high in many markets, creating more negotiating room for buyers willing to proceed despite the higher borrowing cost environment.
Refinancing activity has shown particular sensitivity to this rate increase, with homeowners who previously locked in lower rates having significantly reduced incentive to refinance under current conditions, potentially affecting mortgage lender revenue streams dependent on this business segment.
Regional housing markets may experience varying impacts from this rate environment, with areas that had seen the most significant price appreciation potentially facing greater affordability pressure compared to markets with more moderate historical price growth patterns.
Housing industry stakeholders continue monitoring whether the Federal Reserve’s projected additional rate increase materializes before year end, since further tightening could compound current affordability challenges facing prospective homebuyers already navigating this more expensive borrowing environment.
As the housing market adjusts to this new rate reality, real estate professionals across the country will be watching closely for signs of how buyer behavior evolves. This rate increase adds a significant new variable to housing market dynamics heading into the final months of the year.
