
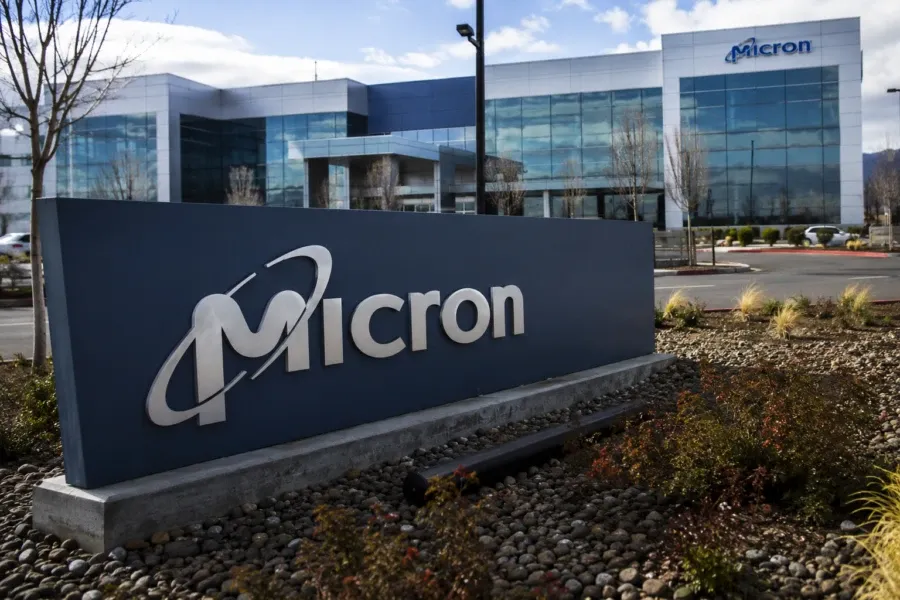
Micron Technology is scheduled to release its fourth-quarter earnings results tomorrow after markets close, an announcement that industry analysts widely view as an important test of whether the artificial intelligence infrastructure spending boom that has powered much of this year’s technology sector gains remains as robust as current investor expectations suggest. Analysts currently project earnings per share around thirty-one dollars and fifteen cents, alongside revenue expectations approaching fifty billion dollars, figures that would represent substantial growth reflecting the company’s central role supplying memory chips essential to AI computing infrastructure.
The memory chip sector has experienced extraordinary demand growth throughout this year, driven substantially by the massive computing infrastructure buildout major technology companies have undertaken to support increasingly sophisticated artificial intelligence systems. High-bandwidth memory specifically has become particularly valuable within this AI infrastructure ecosystem, with Micron positioned as one of the relatively few global suppliers capable of manufacturing these specialized components at the scale and technical specifications required by major AI computing customers.
Investors will be watching tomorrow’s results closely for several key indicators beyond simply whether the company meets or exceeds current analyst projections. Forward guidance regarding future demand trends will likely prove particularly significant, given ongoing market debate about whether current elevated levels of AI infrastructure investment across the technology industry represent a sustainable long-term trend or potentially reflect a temporary surge that could eventually moderate as major technology companies complete their most immediate infrastructure buildout needs.
Pricing trends within the memory chip market represent another important element investors will scrutinize closely, given how directly memory chip pricing affects both Micron’s own profitability and broader cost structures across the technology industry more generally. Sustained strong pricing, reflecting continued tight supply relative to demand, would suggest the current AI infrastructure investment cycle remains firmly intact, while any signs of pricing softness could raise questions about whether supply is beginning to catch up with the extraordinary demand growth witnessed throughout the current year.
The broader semiconductor industry has shown remarkable strength throughout this year, with multiple companies posting extraordinary revenue and profit growth as demand for AI-related computing hardware has shown no clear signs of slowing despite periodic questions about the ultimate sustainability of current spending levels. Micron’s specific results tomorrow will provide one particularly important data point within this broader industry narrative, given the company’s specific exposure to the memory chip segment that has proven especially critical to AI computing infrastructure requirements.
Some analysts have expressed caution about extrapolating too heavily from any single company’s quarterly results, noting that the broader AI infrastructure investment story involves numerous interconnected companies and technologies extending well beyond memory chips specifically. Nevertheless, given Micron’s particular position within this ecosystem, tomorrow’s results will likely receive outsized attention from investors seeking to calibrate their broader expectations regarding the health and sustainability of the current AI-driven technology investment cycle.
As markets await tomorrow’s announcement, the results carry significance extending well beyond Micron’s own stock price, given how closely investors have been watching for signals about whether the broader AI infrastructure spending boom remains fundamentally intact. Strong results and optimistic forward guidance could provide meaningful reassurance to markets that have shown some recent nervousness about AI-related valuations, while any disappointing signals could potentially trigger broader reassessment of assumptions underlying much of this year’s technology sector performance.
